Huang WAYYY!Down?

Visualised & illustrated by brat.kom for Invexor Labs · invexor.ai
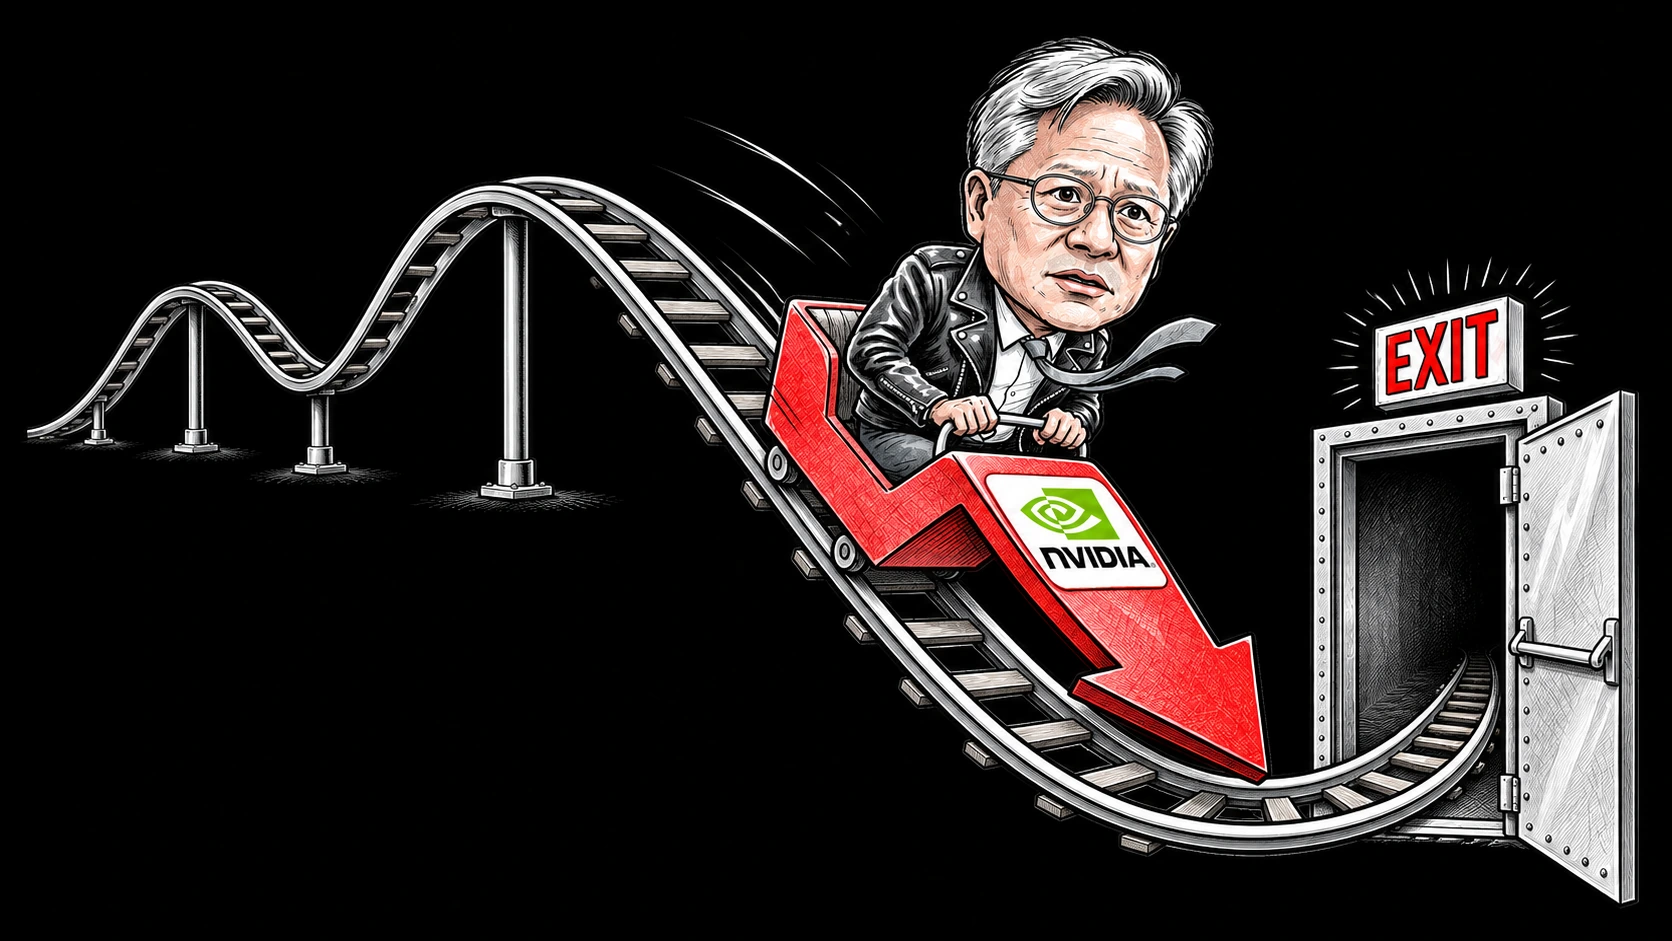
NVIDIA: $115.8bn in quarterly sales. Roughly $2T off October’s peak by 19 Nov. Colette Kress takes the interim CEO seat.
PAGES 04–08Bank up. IT down.
PAGE 02Nifty Bank +3.30% · Nifty IT −3.17%. Week to 13 Nov
Van Hollen challenges Schumer.
PAGE 03A leadership fight inside the new Senate majority.
Seven giants. All red.
PAGES 06–0816 Nov: NVIDIA −4.12% · Alphabet −4.07%. + 19 Nov top 20
Claude sells. Compute collects.
PAGES 09–10$33.24bn sales · $18.81bn compute + infrastructure. 9M 2026
Inflation hits 6.09%.
PAGE 11India CPI · October 2026.
Love the app. Read the invoice.
PAGE 12Follow customer cash to chip + cloud suppliers.
 INDIA

Flat Nifty. Wild Week.
| Group | Index | Segment | 13 Nov close | 1-wk change % |
|---|---|---|---|---|
| Equity | Nifty 50 | Large-cap | 25,144.30 | +0.46% |
| Equity | Nifty 500 | Broad market | 23,734.20 | +1.18% |
| Equity | Nifty Next 50 | Large-cap · next 50 | 72,874.70 | +1.70% |
| Equity | Nifty Midcap 150 | Mid-cap | 22,681.25 | +1.84% |
| Equity | Nifty Smallcap 250 | Small-cap | 17,940.55 | +3.19% |
| Equity | Nifty Bank | Banking | 61,034.10 | +3.30% |
| Equity | Nifty IT | Tech | 31,931.15 | −3.17% |
| Volatility | India VIX | Volatility | 15.50 | −11.28% |
Weekly change: 6–13 Nov 2026. Equity bars share a 0–5% scale; India VIX measures expected volatility.
Competing Forces. Post-midterm relief and foreign inflows lifted Indian equities early in the week, before rising Brent crude and Thursday evening’s October inflation print pulled benchmarks back on Friday.
Beneath the Surface. A nearly flat headline index masked a wide rotation: domestic banks and smaller companies advanced while export-heavy software stocks gave back part of their recent run.
Huang & the Chinese (AI) Models.
with Chinese models.
by Moonshot AI, right?
Way more open-sourced!
DeepSeek and Qwen?
The joke landed because the news was no joke. Huang resigned on 12 November after reports of affairs, including one with a woman suspected of links to Chinese intelligence. Reuters reported the allegations; Beijing denied she was a spy. NVIDIA’s resignation notice gave no reason.
The board changed the wiring. CFO Colette Kress became interim CEO and Harvey Jones took the chair. On 17 November, a new board committee took oversight of national security and export controls, with compliance teams reporting to it and Kress. That changes who answers for the risk.
Why shareholders should care. Our reading: the exposure runs beyond the founder’s reputation. Tighter scrutiny can affect which customers receive chips and how quickly revenue arrives. Watch the permanent CEO appointment, investigation findings and export permissions. A committee is a governance response; it is not proof that the underlying risk is resolved.
Imagined comic dialogue · Reporting: Reuters, 12 Nov · Company notices: 12 & 17 Nov.
Huang WAYYYY Down!
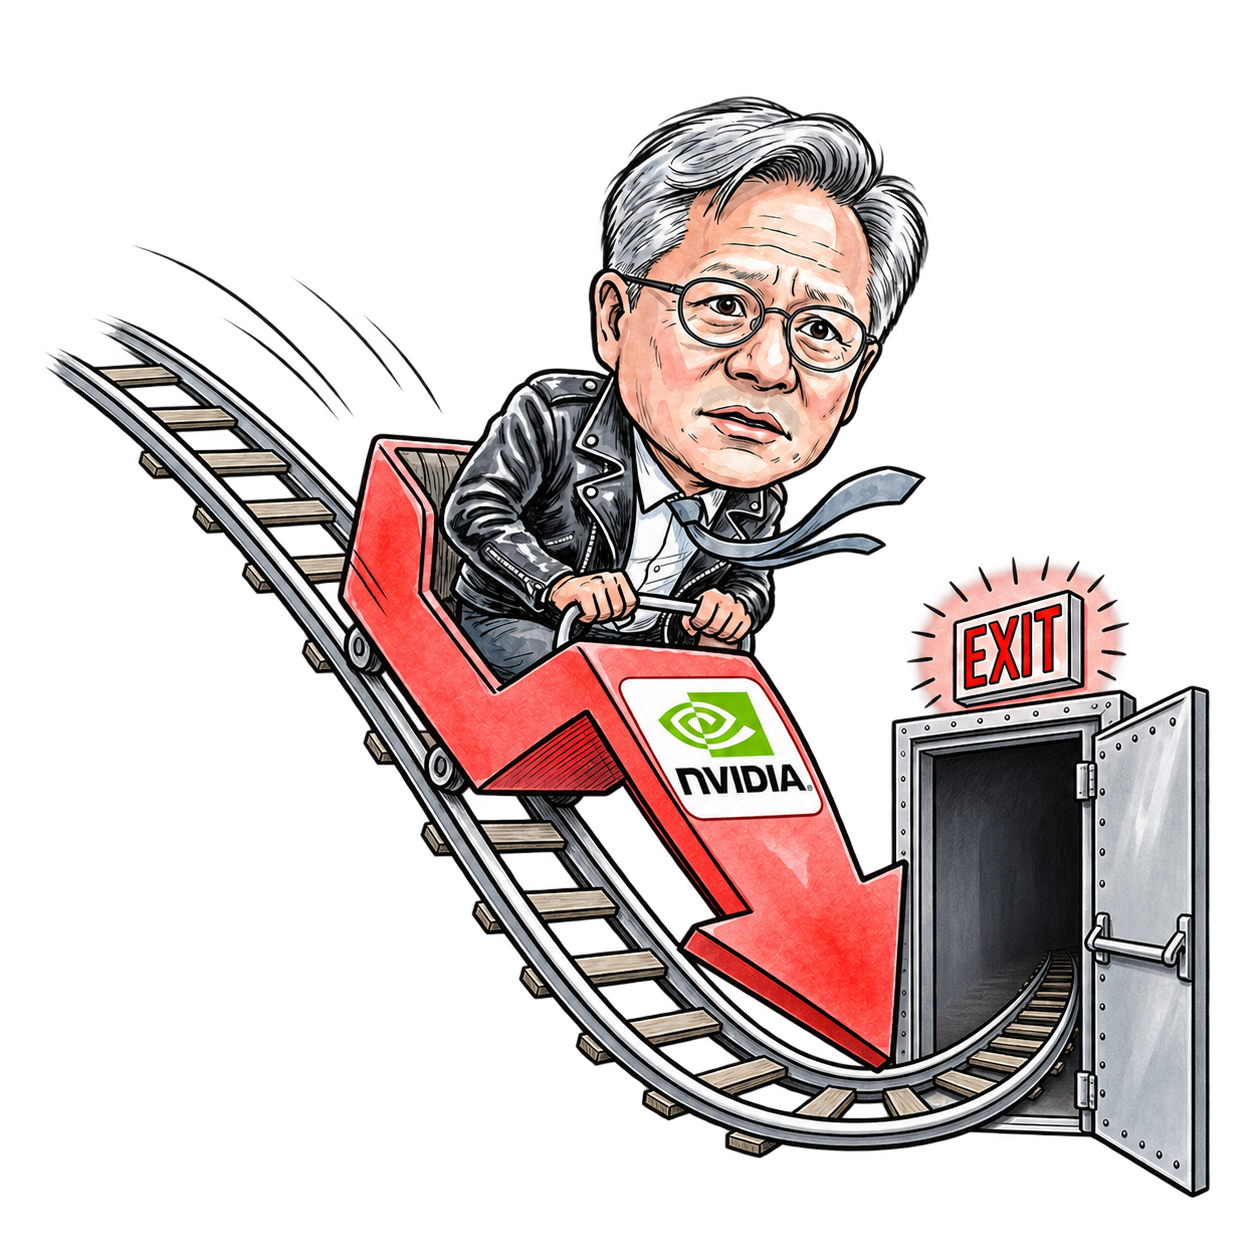
More profit. Less faith. After earnings, analysts lifted next-year adjusted profit estimates from $380bn to $393bn, yet cut their average price target from $265.70 to $251.74. That is the twist: the business forecast improved while the price investors might pay for it fell.
The bill gets bigger. Supply commitments rose from $279bn to $390bn, mainly for multiyear memory supply. Securing scarce inputs can protect deliveries. If demand disappoints, those promises can become a burden. They are purchase obligations—not a customer order book.
China is out of the forecast. Q3 included $2.4bn of China Hopper shipments; Q4 guidance assumes no China data-centre compute revenue. That limits the near-term sales assumption, while leaving the longer-term market-access question open.
Visualised & illustrated by brat.kom for Invexor Labs · invexor.ai
THE MARGIN CATCH
Q3 GAAP gross margin: 74.8%. Q4 guide: 71–72%. At the $130bn revenue midpoint, each margin point is $1.3bn of gross profit. The quarter has an extra week; revenue growth alone is an incomplete scorecard.
WHAT WOULD CHANGE THE STORY?
Our test: deliveries stay on schedule, margins stabilise and customer cash catches up with capacity commitments. Q3’s $115.8bn sales ended on 25 October—before the handover. Strong past sales buy time; they do not settle succession risk.
Peak-to-snapshot decline, not a one-day loss. Illustration is satire. Reuters/LSEG; NVIDIA Q3 release & CFO commentary; 19 Nov CompaniesMarketCap snapshot.
Seven giants. One red session. Seven different drops.
Visualised & illustrated by brat.kom for Invexor Labs · invexor.ai
Huang resigns.
Kress becomes interim CEO.
Nasdaq Composite −2.49%.
All seven stocks fall.
NVIDIA reports $115.8bn sales.
The quarter predates the exit.
Love Claude. Dread the Bill.
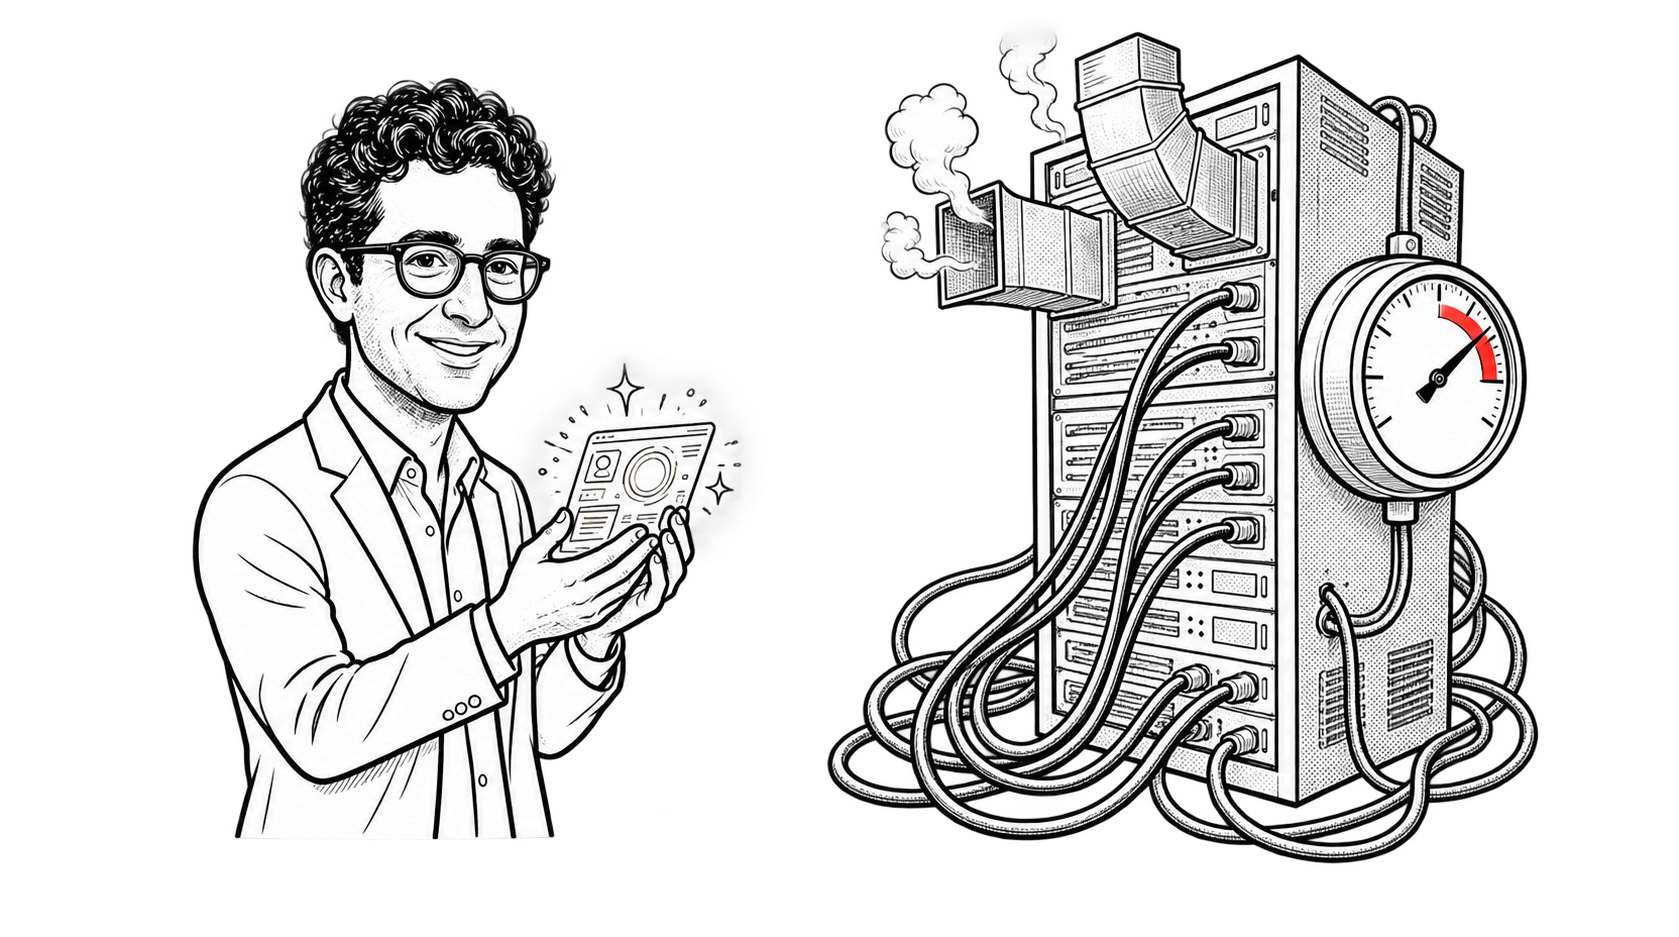
Editorial caricature showing the economic tension in frontier AI scaling.
Anthropic reported $33.24bn in revenue for the nine months to September 2026. Compute and infrastructure consumed $18.81bn—before the other costs of running the business.
Its purchase and lease commitments total $900.9bn, including $70.7bn due within 12 months of 30 September. Those are future commitments, not today’s expense. The bet: demand grows into the infrastructure already promised.
Backers. And Billers.
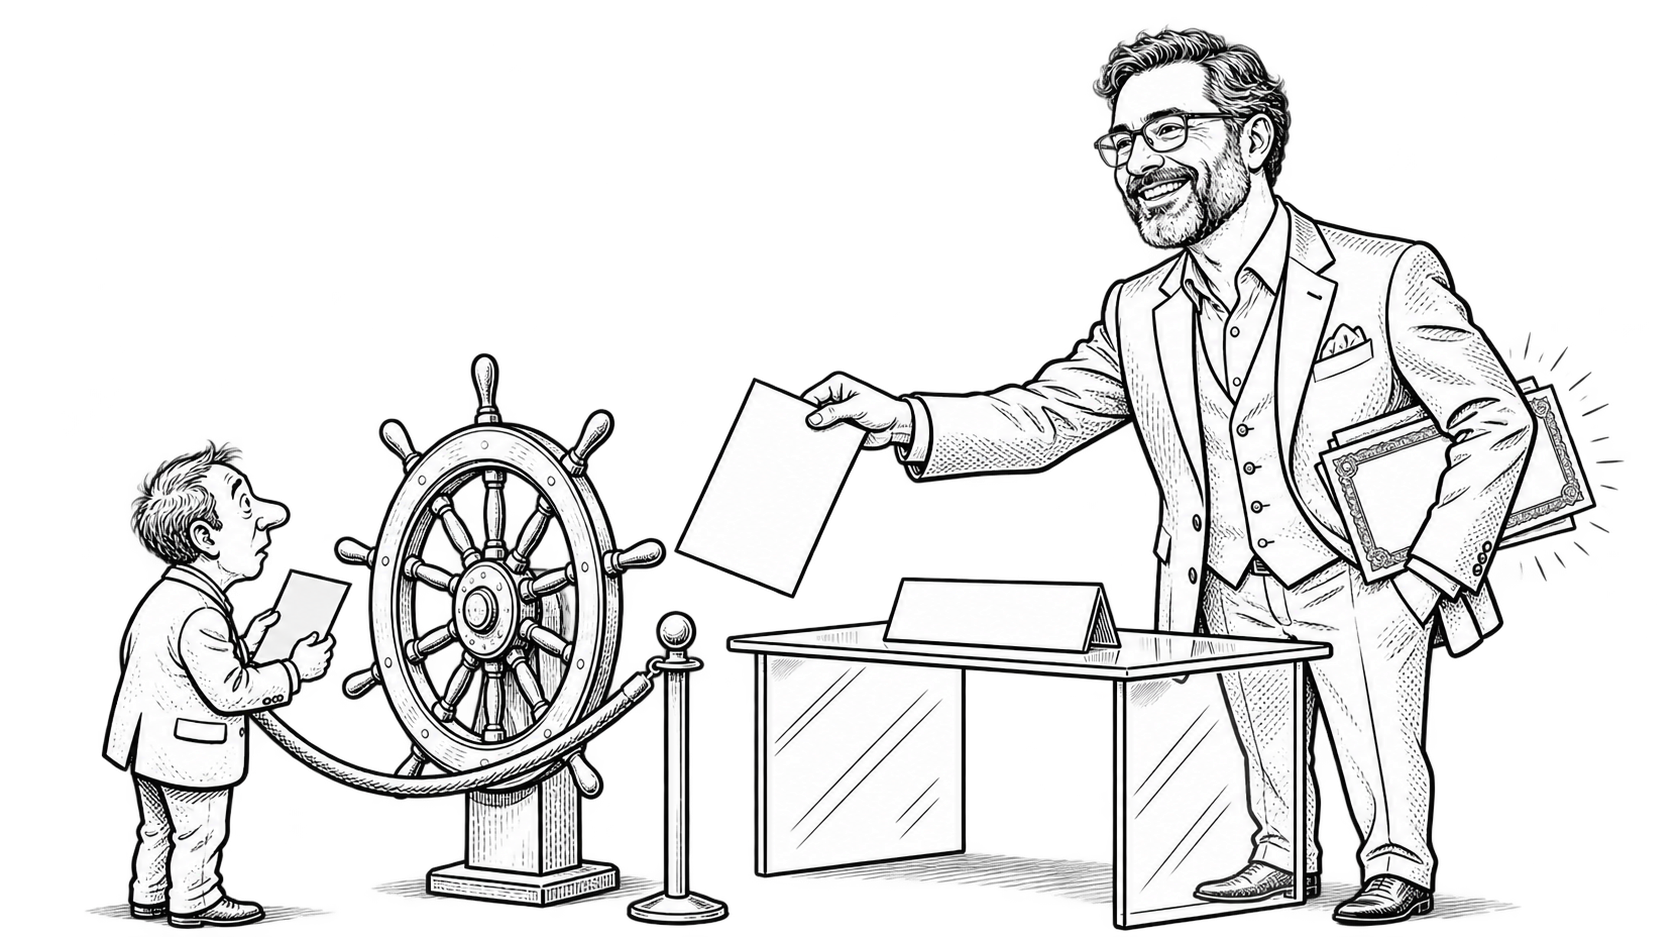
Editorial metaphor of multi-class governance and supplier incentives.
Strategic partners proposing to buy $26bn of non-voting Class N stock also supply the chips and cloud compute Anthropic needs. Public Class A buyers (1 vote/share) face different incentives.
Meanwhile, Class F holds 50.1% general voting power and the Long-Term Benefit Trust (Class T) elects a board majority. Public capital helps fund the compute without steering the ship.
INDIA
Oil at sea won’t fill your tank.
Barrels at sea ≠ cheap diesel; hot CPI can limit rate-cut room.
follow the invoice.
We pay too much attention to who holds the microphone and too little to who sends the invoice. An AI product can win affection while its suppliers capture the economics. A company can sell you shares while keeping control elsewhere.
That doesn’t make every ambitious business a bad investment. Scale, software and disciplined execution can produce remarkable value. It means applause is the beginning of research, not the conclusion.
My question for the next wave of AI companies is simple: when the customer pays, who gets paid next—and who keeps what remains? Follow that trail. It tells you more than the launch stage.
Visualised & illustrated by brat.kom for Invexor Labs · invexor.ai